Fixed Income / Credit
U.S. High-Yield Strategy (USHY)
A well-researched approach to high-yield investing. Invests in a diversified portfolio of lower rated, higher yielding bonds with a focus on income and the potential for capital appreciation. The high-yield investment team benefits from the extensive research capabilities of Capital's equity and macroeconomic analysts.
Overview
Key information
Investment Objectives
Seeks to provide a high level of current income. Its secondary investment objective is capital appreciation.
Types of Investment
At least 80% of the portfolio will be invested in high-yield, lower rated bonds (BB+/Ba1 or below at the time of purchase) and other similar securities.
Distinguishing Characteristics 9
The strategy invests in a diversified portfolio of lower rated, higher yielding bonds with a focus on income and the potential for capital appreciation. A dedicated team of analysts, traders and portfolio managers collaborate to achieve a comprehensive understanding of a company's financial position and capital structure via fundamental bottom-up analysis. The high-yield investment team benefits from the extensive research capabilities across Capital's equity and macroeconomic analysts.
Holdings Outside the U.S.
A portion of the portfolio's assets may be invested in securities of issuers outside the U.S., which may be denominated in currencies other than the U.S. dollar.
Portfolio Managers8
Portfolio managers' years of experience are as of the previous calendar year end.
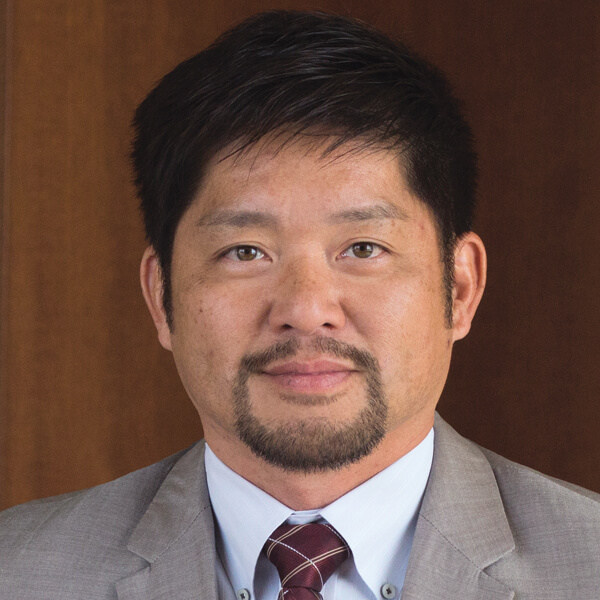
Tom Chow
37 years of investment industry experience
11 years with Capital Group
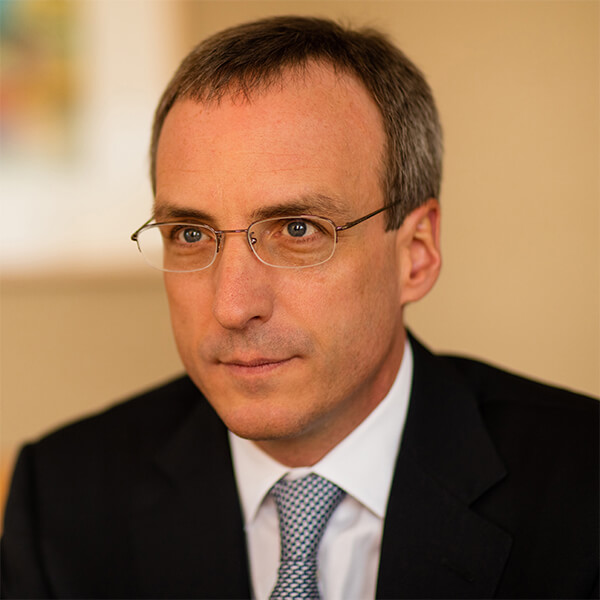
David Daigle
Principal Investment Officer
31 years of investment industry experience
31 years with Capital Group
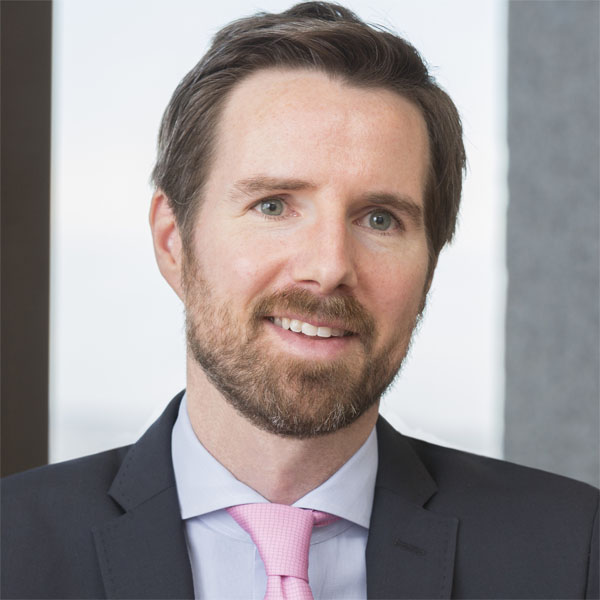
Andy Moth
22 years of investment industry experience
9 years with Capital Group
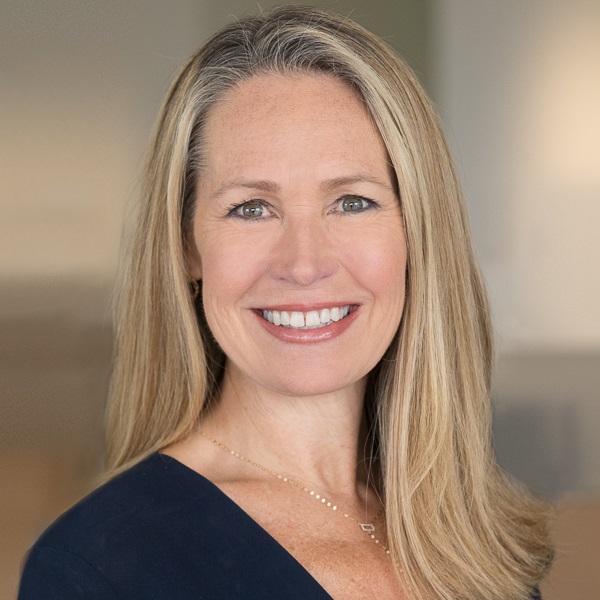
Shannon Ward
33 years of investment industry experience
9 years with Capital Group
Returns
Investment results1, 2, 3, 4, 5, 6, 7
Total returns for periods ended 9/30/26 (%)
- ●Gross
- ●Net
- ●Index
| STRATEGY | 1M | 3M | YTD | 1Y | 3Y | 5Y | 7Y | 10Y | 15Y | 20Y | Lifetime |
|---|
Index data refers to the Bloomberg U.S. Corporate High Yield 2% Issuer Capped Indextooltip: Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index covers the universe of fixed-rate, non-investment-grade debt. The index limits the maximum exposure of any one issuer to 2%. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes..
Strategy inception: 02/29/1984. Index lifetime is based on inception date of
the strategy.
Risk measures5, 11
As of 9/30/26 (updated monthly)
| Standard deviationtooltip: Annualized standard deviation (based on monthly returns) is a common measure of absolute volatility that tells how returns over time have varied from the mean. A lower number signifies lower volatility. | |
| USHY (gross/net %) | 4.51/4.51 |
| Bloomberg U.S. Corporate High Yield 2% Issuer Capped Indextooltip: Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index covers the universe of fixed-rate, non-investment-grade debt. The index limits the maximum exposure of any one issuer to 2%. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes. | — |
| Sharpe ratiotooltip: Sharpe ratios use standard deviation and excess return to determine reward per unit of risk. The higher the number, the better the portfolio's historical risk-adjusted performance. | |
| USHY (gross/net %) | 0.93/0.85 |
| Bloomberg U.S. Corporate High Yield 2% Issuer Capped Indextooltip: Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index covers the universe of fixed-rate, non-investment-grade debt. The index limits the maximum exposure of any one issuer to 2%. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes. | 0.74 |
Data calculated against the Bloomberg U.S. Corporate High Yield 2% Issuer Capped Indextooltip: Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index covers the universe of fixed-rate, non-investment-grade debt. The index limits the maximum exposure of any one issuer to 2%. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes.unless noted otherwise. | |
| R-squared (gross/net)tooltip: R-squared is a measure of the correlation between a particular return and that of a benchmark index. A measure of 100 indicates that all of the return can be explained by movements in the benchmark. Generally the higher the R-squared measure, the more reliable the beta measurement will be. | 96/96 |
| Alpha (gross/net)tooltip: Alpha is a measure of the difference between a portfolio's actual returns and its expected results, given its level of risk as measured by beta. A positive alpha figure indicates the portfolio has performed better than its beta would predict. In contrast, a negative alpha indicates the portfolio has underperformed, given the expectations established by beta. | 0.96/0.64 |
| Beta (gross/net)tooltip: Beta relatively measures sensitivity to market movements over a specified period of time. The beta of the market (represented by the benchmark index) is equal to 1; a beta higher than 1 implies that a return was more volatile than the market. A beta lower than 1 suggests that a return was less volatile than the market. Generally the higher the R-squared measure, the more reliable the beta measurement will be. | 0.98/0.98 |
| Information ratio (gross/net)tooltip: The information ratio represents the excess return generated (over the market) per unit of relative risk as measured by tracking error. | 1.01/0.61 |
| Downside capture ratio (gross/net)tooltip: Ratio of a portfolio/composite's return during periods when the index was down, divided by the return of the index during those periods. For example, during periods when the index was down, a down-capture ratio greater than 100 indicates the portfolio/composite produced a lower return than the index. | 89/92 |
| Upside capture ratio (gross/net)tooltip: Ratio of a portfolio/composite's return during periods when the index was up, divided by the return of the index during those periods. For example, an up-capture ratio greater than 100 indicates the portfolio/composite produced a higher return than the index during periods when the index was up. | 105/103 |
| Tracking error (gross/net %)tooltip: The tracking error is the standard deviation of the difference between the returns of an investment and its benchmark. | 0.88/0.88 |
| S&P 500 correlation (gross/net)tooltip: Correlation describes the strength of the association between a return and a benchmark. Correlation is shown on a scale from 1 to -1. The higher the positive correlation, the more closely the return and the benchmark moved relative to one another. The lower the negative correlation, the more the return and the benchmark diverged from one another. | 0.71/0.71 |
| MSCI ACWI correlation (gross/net)tooltip: Correlation describes the strength of the association between a return and a benchmark. Correlation is shown on a scale from 1 to -1. The higher the positive correlation, the more closely the return and the benchmark moved relative to one another. The lower the negative correlation, the more the return and the benchmark diverged from one another. | 0.76/0.76 |
Portfolio Composition
Asset mix
As of 9/30/26 (updated monthly)
U.S. Equities | 3.5% |
|---|---|
Non-U.S. Equities | 0.3% |
U.S Bonds | 79.6% |
Non-U.S. Bonds | 10.3% |
Cash, Equivalents & Other10 | 6.2% |
U.S. Equities | 3.5% |
|---|---|
Non-U.S. Equities | 0.3% |
U.S Bonds | 79.6% |
Non-U.S. Bonds | 10.3% |
Cash, Equivalents & Other10 | 6.2% |
Key statistics
As of 9/30/26 (updated monthly)
USHY | INDEX | |
|---|---|---|
Yield to worsttooltip: Lower of Yield to Maturity or the bond's total return if put or call options are exercised prior to maturity but no default occurs. (gross/net %)12 | 7.5/7.2 | 8.2 |
Yield to maturitytooltip: A bond's total return if held to maturity and no default occurs or options are exercised. Assumes coupons are paid on time and accounts for their present value. Assumes principal is returned at maturity. (gross/net %)12 | 7.7/7.4 | 8.4 |
Average coupontooltip: The average coupon is the weighted average coupon rate of all the bond holdings. (gross/net %)12 | 6.2/5.9 | 6.8 |
Effective durationtooltip: Effective duration is a duration calculation for bonds that takes into account that expected cash flows will fluctuate as interest rates change. (years) | 3.1 | 3.3 |
Spread durationtooltip: A measure of fixed income securities' sensitivity to spread movement. (years) | 3.2 | 3.3 |
Option adjusted spreadtooltip: Option-adjusted spread is a yield-spread calculation used to value securities with embedded options. (bps) | 261.2 | 298 |
Duration times spreadtooltip: A measure of fixed income securities' spread exposure, taking into account both spread duration and credit spread exposure. (bps) | 842 | 950 |
Index data refers to the Bloomberg U.S. Corporate High Yield 2% Issuer Capped Indextooltip: Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index covers the universe of fixed-rate, non-investment-grade debt. The index limits the maximum exposure of any one issuer to 2%. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes..
Top fixed income issuers13
As of 9/30/26 (updated monthly)
USHY
Index
| USHY | Index | |
|---|---|---|
| Charter Communications | 3.2% | 1.6% |
| Viasat | 2.1% | 0.2% |
| Ford Motor | 1.9% | — |
| Venture Global Partners II | 1.9% | 1.8% |
| EchoStar | 1.7% | 0.6% |
| TransDigm Group | 1.5% | 1.6% |
| Nexstar Media Group | 1.3% | 0.4% |
| Navient | 1.3% | 0.3% |
| Medical Properties Trust | 1.3% | 0.2% |
| Service Properties | 1.2% | 0.2% |
Index data refers to the Bloomberg U.S. Corporate High Yield 2% Issuer Capped Indextooltip: Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index covers the universe of fixed-rate, non-investment-grade debt. The index limits the maximum exposure of any one issuer to 2%. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes..
Portfolio exposures
As of 9/30/26 (updated monthly)
| Market value (%) | |||
|---|---|---|---|
| Sectors and top holdings | USHY | INDEX | |
| Credit | 84.2 | 92.7 | |
| Treasuries & agencies16 | 0.0 | — | |
| Other17 | 3.8 | — | |
| Cash & equivalents14 | 4.7 | — | |
| CDXtooltip: The credit default swap index (CDX) is a benchmark financial instrument made up of credit default swaps (CDS) that have been issued by North American or emerging markets companies. Credit default swaps act like insurance policies offering a buyer protection in case of the borrower's default.& TRStooltip: A total return swap (TRS) is a contract between a total return payer and total return receiver. The payer usually pays the total return of agreed security to the receiver and receives a fixed/floating rate payment in exchange. The agreed (or referenced) security can be a bond, index, equity, loan, or commodity. Offset18 | -0.3 | — | |
Index data refers to the Bloomberg U.S. Corporate High Yield 2% Issuer Capped Indextooltip: Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index covers the universe of fixed-rate, non-investment-grade debt. The index limits the maximum exposure of any one issuer to 2%. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes..
Resources
Literature
For institutional investors and registered investment advisors only. Not for use with the public.
Figures shown are past results and are not predictive of results in future periods. Current and future results may be lower or higher than those shown. Investing for short periods makes losses more likely.
Prices and returns will vary, so investors may lose money.
View strategy returns.
Investments are not FDIC-insured, nor are they deposits of or guaranteed by a bank or any other entity, so they may lose value.
Important information about objectives, risks, charges and expenses for collective investment trusts is contained in the Characteristics Statement and/or other fund disclosure document(s), which can be obtained from the fund's trustee and/or the participants' plan provider or employer.
Data based on the representative account of the Capital Group U.S. High-Yield Composite, unless otherwise noted.
Bond ratings, which typically range from AAA/Aaa (highest) to D (lowest), are assigned by credit rating agencies such as Standard & Poor's, Moody's and/or Fitch, as an indication of an issuer's creditworthiness.
Consistent with applicable investment policies, a security will be considered to have received the middle rating. If only two agencies rate a security, the lower rating is used. If only one rates a security, that single rating is used. Securities in the Unrated category have not been rated by any of the rating agencies referenced above; however, the investment adviser performs its own credit analysis and assigns comparable ratings that are used for compliance with applicable investment policies.
The return of principal for bond portfolios and portfolios with significant underlying bond holdings is not guaranteed. Investments are subject to the same interest rate, inflation and credit risks associated with the underlying bond holdings.
Lower rated bonds are subject to greater fluctuations in value and risk of loss of income and principal than higher rated bonds.
Investing outside the United States involves risks, such as currency fluctuations, periods of illiquidity and price volatility. These risks may be heightened in connection with investments in developing countries.
There have been periods when the results lagged the index(es) and/or average(s).
The indexes are unmanaged and, therefore, have no expenses. Investors cannot invest directly in an index.
Bloomberg Index Services Limited. BLOOMBERG® is a trademark and service mark of Bloomberg Finance L.P. and its affiliates (collectively "Bloomberg"). Bloomberg or Bloomberg's licensors own all proprietary rights in the Bloomberg Indices. Neither Bloomberg nor Bloomberg's licensors approves or endorses this material, or guarantees the accuracy or completeness of any information herein, or makes any warranty, express or implied, as to the results to be obtained therefrom and, to the maximum extent allowed by law, neither shall have any liability or responsibility for injury or damages arising in connection therewith.
All Capital Group trademarks mentioned are owned by The Capital Group Companies, Inc., an affiliated company or fund. All other company and product names mentioned are the property of their respective companies.
Portfolios are managed, so holdings will change.
Holdings mentioned and their results are not representative of other holdings in the portfolio or the portfolio's results.
Certain fixed income and/or cash and equivalents holdings may be held through mutual funds managed by the investment adviser or its affiliates that are not offered to the public.
Totals may not reconcile due to rounding and/or cash flows.
Investment results assume all distributions are reinvested and reflect applicable fees and expenses.
1.
YTD (year-to-date return): For the period from January 1 of the current year to the date shown or from inception date if first offered after January 1 of the current year.
2.
When applicable, returns for less than one year are not annualized, but calculated as cumulative total returns.
3.
Gross composite results do not reflect the deduction of fees and expenses; results would have been lower if they were subject to fees and expenses.
4.
Returns are in USD. Returns reflect the reinvestment of dividends, interest and other earnings.
5.
Data reflect the Capital Group U.S. High-Yield Composite.
6.
Composite returns are net of withholding taxes on dividends, interest and capital gains. Actual withholding tax rates vary according to the country of denomination and tax status of each portfolio.
7.
Composite net results are calculated by deducting from the gross results a model fee equal to the highest management fees for applicable composite members. Actual fees may vary depending on, among other things, the applicable fee schedule and portfolio size.
8.
Reflects current team at the time of publication. Years of experience in investment industry and Capital Group are as of the most recent year end.
9.
Capital Group manages equity assets through three investment groups. These groups make investment and proxy voting decisions independently. Fixed income investment professionals provide fixed income research and investment management across the Capital organization; however, for securities with equity characteristics, they act solely on behalf of one of the three equity investment groups.
10.
Includes cash, short-term securities, other assets less liabilities, and certain accruals. It may also include investments in money market or similar funds managed by the investment adviser or its affiliates that are not offered to the public.
11.
Risk measures net of fees are based on net results which are calculated using a model fee equal to the highest management fee for applicable composite members deducted from the gross results, which do not reflect the deduction of fees and expenses.
12.
Based on the representative account for the applicable composite. Refer to composite results disclosures for descriptions of fees used to calculate yield measures shown. Defaults by fixed income issuers would result in different, lower realized yields. Past results are not predictive of results in future periods.
13.
The information shown does not include cash and equivalents. Cash and equivalents may include investments in money market or similar funds managed by a third party or similar investments managed by the investment adviser or its affiliates that are not offered to the public.
14.
Includes cash, short-term securities, other assets less liabilities, and certain accruals. It may also include investments in money market or similar funds managed by the investment adviser or its affiliates that are not offered to the public.
15.
Portfolio market value reflect risk notional values. Risk notional is the value of the underlying asset at the current market price for a derivatives trade.
16.
Treasuries and agencies may include swaps and futures.
17.
Sector breakdown "Other" may include equities, rights, warrants, preferreds, convertibles, forwards, the market value of certain derivative instruments and other uncategorized securities.
18.
The offset represents positions within the portfolio used to offset risk and is -1 multiplied by the total of all notional values.
19.
Includes cash, short-term securities, other assets less liabilities, and may include accrued income. It may also include investments in money market or similar funds managed by the investment adviser or its affiliates that are not offered to the public.
20.
Rating exposure ”Other” may include equities, rights, warrants, preferreds, convertibles, forwards and FX (foreign exchange) options.
Collective Investment Trusts (CITs) are available for investment only to certain qualified retirement plans. Capital Group CITs are maintained by Capital Bank and Trust Company (“trustee”), which has retained an affiliate to serve as investment adviser to the trustee.
Advisory services offered through Capital Research and Management Company (CRMC) and its RIA affiliates.
Use of this website is intended for U.S. residents only.
Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index
Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index covers the universe of fixed-rate, non-investment-grade debt. The index limits the maximum exposure of any one issuer to 2%. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes.
Bloomberg U.S. Corporate High Yield 2% Issuer Capped Index covers the universe of fixed-rate, non-investment-grade debt. The index limits the maximum exposure of any one issuer to 2%. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes.
Alpha
Alpha is a measure of the difference between a portfolio's actual returns and its expected results, given its level of risk as measured by beta. A positive alpha figure indicates the portfolio has performed better than its beta would predict. In contrast, a negative alpha indicates the portfolio has underperformed, given the expectations established by beta.
Alpha is a measure of the difference between a portfolio's actual returns and its expected results, given its level of risk as measured by beta. A positive alpha figure indicates the portfolio has performed better than its beta would predict. In contrast, a negative alpha indicates the portfolio has underperformed, given the expectations established by beta.
Average coupon
The average coupon is the weighted average coupon rate of all the bond holdings.
The average coupon is the weighted average coupon rate of all the bond holdings.
Beta
Beta relatively measures sensitivity to market movements over a specified period of time. The beta of the market (represented by the benchmark index) is equal to 1; a beta higher than 1 implies that a return was more volatile than the market. A beta lower than 1 suggests that a return was less volatile than the market. Generally the higher the R-squared measure, the more reliable the beta measurement will be.
Beta relatively measures sensitivity to market movements over a specified period of time. The beta of the market (represented by the benchmark index) is equal to 1; a beta higher than 1 implies that a return was more volatile than the market. A beta lower than 1 suggests that a return was less volatile than the market. Generally the higher the R-squared measure, the more reliable the beta measurement will be.
Effective duration
Effective duration is a duration calculation for bonds that takes into account that expected cash flows will fluctuate as interest rates change.
Effective duration is a duration calculation for bonds that takes into account that expected cash flows will fluctuate as interest rates change.
Bond Statistic Net Coupon
The average coupon is the weighted average coupon rate of all the bond holdings.
The average coupon is the weighted average coupon rate of all the bond holdings.
Bond Statistic Net Yield to Maturity
A bond's total return if held to maturity and no default occurs or options are exercised. Assumes coupons are paid on time and accounts for their present value. Assumes principal is returned at maturity.
A bond's total return if held to maturity and no default occurs or options are exercised. Assumes coupons are paid on time and accounts for their present value. Assumes principal is returned at maturity.
Bond Statistic Net Yield to Worst
Lower of Yield to Maturity or the bond's total return if put or call options are exercised prior to maturity but no default occurs.
Lower of Yield to Maturity or the bond's total return if put or call options are exercised prior to maturity but no default occurs.
Option adjusted spread
Option-adjusted spread is a yield-spread calculation used to value securities with embedded options.
Option-adjusted spread is a yield-spread calculation used to value securities with embedded options.
Yield to maturity
A bond's total return if held to maturity and no default occurs or options are exercised. Assumes coupons are paid on time and accounts for their present value. Assumes principal is returned at maturity.
A bond's total return if held to maturity and no default occurs or options are exercised. Assumes coupons are paid on time and accounts for their present value. Assumes principal is returned at maturity.
Yield to worst
Lower of Yield to Maturity or the bond's total return if put or call options are exercised prior to maturity but no default occurs.
Lower of Yield to Maturity or the bond's total return if put or call options are exercised prior to maturity but no default occurs.
Credit Default Swap Index
The credit default swap index (CDX) is a benchmark financial instrument made up of credit default swaps (CDS) that have been issued by North American or emerging markets companies. Credit default swaps act like insurance policies offering a buyer protection in case of the borrower's default.
The credit default swap index (CDX) is a benchmark financial instrument made up of credit default swaps (CDS) that have been issued by North American or emerging markets companies. Credit default swaps act like insurance policies offering a buyer protection in case of the borrower's default.
Currency Weighting Short Breakdown
The exposure to a specific currency before taking into consideration any forward currency contracts that may increase or decrease that currency's exposure.
The exposure to a specific currency before taking into consideration any forward currency contracts that may increase or decrease that currency's exposure.
Downside capture ratio
Ratio of a portfolio/composite's return during periods when the index was down, divided by the return of the index during those periods. For example, during periods when the index was down, a down-capture ratio greater than 100 indicates the portfolio/composite produced a lower return than the index.
Ratio of a portfolio/composite's return during periods when the index was down, divided by the return of the index during those periods. For example, during periods when the index was down, a down-capture ratio greater than 100 indicates the portfolio/composite produced a lower return than the index.
Duration times spread
A measure of fixed income securities' spread exposure, taking into account both spread duration and credit spread exposure.
A measure of fixed income securities' spread exposure, taking into account both spread duration and credit spread exposure.
Portfolio turnover
Portfolio turnover is the portion of a portfolio's holdings sold and replaced with new securities annually, usually expressed as a percentage of the portfolio's total assets. For example, a portfolio with a turnover of 25% holds assets for an average of about four years, while a portfolio with a turnover of 100% holds assets for one year.
Portfolio turnover is the portion of a portfolio's holdings sold and replaced with new securities annually, usually expressed as a percentage of the portfolio's total assets. For example, a portfolio with a turnover of 25% holds assets for an average of about four years, while a portfolio with a turnover of 100% holds assets for one year.
Index Correlation
Correlation describes the strength of the association between a return and a benchmark. Correlation is shown on a scale from 1 to -1. The higher the positive correlation, the more closely the return and the benchmark moved relative to one another. The lower the negative correlation, the more the return and the benchmark diverged from one another.
Correlation describes the strength of the association between a return and a benchmark. Correlation is shown on a scale from 1 to -1. The higher the positive correlation, the more closely the return and the benchmark moved relative to one another. The lower the negative correlation, the more the return and the benchmark diverged from one another.
Information ratio
The information ratio represents the excess return generated (over the market) per unit of relative risk as measured by tracking error.
The information ratio represents the excess return generated (over the market) per unit of relative risk as measured by tracking error.
Average excess rolling return
Average excess rolling return is the average of the excess return between the portfolio and the index across all periods for the specified timeframe.
Average excess rolling return is the average of the excess return between the portfolio and the index across all periods for the specified timeframe.
Average rolling index return
Average rolling index return provides the average return for the index across all periods within the specified timeframe.
Average rolling index return provides the average return for the index across all periods within the specified timeframe.
Average lagging rolling return
Average lagged rolling return is the average percentage the portfolio lagged the index in periods where the portfolio return was less than the index for the specified timeframe.
Average lagged rolling return is the average percentage the portfolio lagged the index in periods where the portfolio return was less than the index for the specified timeframe.
Average outpaced rolling return
Average outpaced rolling return is the average percentage the portfolio outpaced the index in periods where the portfolio return was greater than the index for the specified timeframe.
Average outpaced rolling return is the average percentage the portfolio outpaced the index in periods where the portfolio return was greater than the index for the specified timeframe.
Average rolling return
Average rolling return provides the average return for the portfolio across all periods within the specified timeframe.
Average rolling return provides the average return for the portfolio across all periods within the specified timeframe.
Success Rate
The success rate is the percentage of time when the return of a portfolio is greater than the return of its respective index. It is calculated by dividing the number of periods the portfolio outpaced the index by the total number of periods.
The success rate is the percentage of time when the return of a portfolio is greater than the return of its respective index. It is calculated by dividing the number of periods the portfolio outpaced the index by the total number of periods.
R-squared
R-squared is a measure of the correlation between a particular return and that of a benchmark index. A measure of 100 indicates that all of the return can be explained by movements in the benchmark. Generally the higher the R-squared measure, the more reliable the beta measurement will be.
R-squared is a measure of the correlation between a particular return and that of a benchmark index. A measure of 100 indicates that all of the return can be explained by movements in the benchmark. Generally the higher the R-squared measure, the more reliable the beta measurement will be.
Standard deviation
Annualized standard deviation (based on monthly returns) is a common measure of absolute volatility that tells how returns over time have varied from the mean. A lower number signifies lower volatility.
Annualized standard deviation (based on monthly returns) is a common measure of absolute volatility that tells how returns over time have varied from the mean. A lower number signifies lower volatility.
Spread duration
A measure of fixed income securities' sensitivity to spread movement.
A measure of fixed income securities' sensitivity to spread movement.
Sharpe ratio
Sharpe ratios use standard deviation and excess return to determine reward per unit of risk. The higher the number, the better the portfolio's historical risk-adjusted performance.
Sharpe ratios use standard deviation and excess return to determine reward per unit of risk. The higher the number, the better the portfolio's historical risk-adjusted performance.
Tracking error
The tracking error is the standard deviation of the difference between the returns of an investment and its benchmark.
The tracking error is the standard deviation of the difference between the returns of an investment and its benchmark.
Total Return Swap
A total return swap (TRS) is a contract between a total return payer and total return receiver. The payer usually pays the total return of agreed security to the receiver and receives a fixed/floating rate payment in exchange. The agreed (or referenced) security can be a bond, index, equity, loan, or commodity.
A total return swap (TRS) is a contract between a total return payer and total return receiver. The payer usually pays the total return of agreed security to the receiver and receives a fixed/floating rate payment in exchange. The agreed (or referenced) security can be a bond, index, equity, loan, or commodity.
Upside capture ratio
Ratio of a portfolio/composite's return during periods when the index was up, divided by the return of the index during those periods. For example, an up-capture ratio greater than 100 indicates the portfolio/composite produced a higher return than the index during periods when the index was up.
Ratio of a portfolio/composite's return during periods when the index was up, divided by the return of the index during those periods. For example, an up-capture ratio greater than 100 indicates the portfolio/composite produced a higher return than the index during periods when the index was up.